What are ESG Scope 1 and Scope 2

As sustainability reporting becomes mandatory in Singapore, organisations must clearly understand how to classify and measure greenhouse gas (GHG) emissions under internationally recognised standards. The definitions of Scope 1 and Scope 2 are derived from the GHG Protocol and adopted in ISSB/IFRS S2 Climate-related Disclosures, which underpin Singapore’s climate reporting framework.

Emission Calculation Formula

GHG emissions are commonly calculated using the following formula:

Emissions (tCO₂e)  = Activity Data × Emission Factor × Global Warming Potential (if applicable)

Singapore-recommended emission factors are typically sourced from:

  • National Environment Agency (NEA)

  • IPCC (where local factors are unavailable)

Scope 1: Direct Emissions

Scope 1 emissions refer to direct GHG emissions from sources owned or controlled by the organisation. Examples include:

  • Fuel combustion from company-owned vehicles

  • Diesel or natural gas used in generators or boilers

  • Refrigerant leakage from air-conditioning systems

  • Onsite industrial process emissions

Example – Diesel Vehicle

  • Annual diesel usage: 5,000 litres

  • Emission factor: 2.68 kg CO₂e per litre

Emissions = 5,000 × 2.68 = 13,400 kg CO₂e
= 13.4 tCO₂e

Scope 2: Indirect Energy Emissions

Scope 2 emissions cover indirect GHG emissions from purchased electricity, steam, heating or cooling consumed by the organisation. In Singapore, this primarily relates to grid electricity used in offices, warehouses, and factories.

Example – Electricity Consumption

  • Annual electricity use: 50,000 kWh

  • Singapore grid emission factor: 0.408 kg CO₂e per kWh

Emissions = 50,000 × 0.408 = 20,400 kg CO₂e
= 20.4 tCO₂e

Accurately identifying and quantifying emissions is essential for meeting Singapore’s climate reporting requirements and demonstrating environmental accountability. If your organisation requires support in emissions measurement or reporting, our team is ready to assist.


Singapore’s Evolving ESG and Climate-Reporting Requirements

Singapore is entering a new phase of ESG regulation, driven by climate-reporting standards aligned with the ISSB/IFRS framework. The objective is to strengthen transparency, comparability, and market confidence while supporting sustainable finance.

What’s Changing

For SGX-listed companies

  • From FY2025: Mandatory ISSB-aligned climate disclosures, including Scope 1 & 2 emissions.

  • From FY2026: Broader ISSB requirements and mandatory Scope 3 reporting for STI companies.

  • By FY2029: External limited assurance for Scope 1 & 2 emissions.

For large non-listed companies

  • From FY2030: Mandatory ISSB-aligned climate disclosures (Scope 1 & 2) for firms meeting size thresholds.

Why It Matters

  • Listed companies: Must enhance data systems, emissions accounting and governance to meet stricter disclosure and assurance expectations.

  • Large private companies: Need to begin capability-building early due to upcoming obligations.

  • Investors and lenders: Benefit from consistent, comparable and auditable climate information.

  • Singapore’s broader ecosystem: Gains stronger global alignment and improved access to sustainable finance.

Commercial Impact — Procurement

Government and major private buyers now integrate environmental criteria into tender evaluations.
Examples:

  • Government procurement may allocate up to 5% of tender points to environmental factors.

  • Changi Airport Group requires minimum environmental scores to qualify.

  • SMRT assigns a 5% sustainability weighting and requires Scope 3 emissions disclosures from bidders.

ESG compliance is increasingly tied to contract eligibility and competitive advantage.

Conclusion

Singapore’s ESG landscape is advancing rapidly, with mandatory climate disclosures expanding across sectors. Organisations must strengthen reporting capabilities, emissions measurement and governance to stay compliant and competitive.

If your organisation needs support with ESG compliance, climate reporting or tender-readiness, our team can assist at every stage.

IFRS 18: Key Changes and Implications for Singapore Companies Ahead of 2027 Adoption

IFRS 18: Key Changes and Implications for Singapore Companies Ahead of 2027 Adoption

The International Accounting Standards Board (IASB) has issued IFRS 18 – Presentation and Disclosure in Financial Statements, which introduces a fundamental overhaul to how financial performance is presented. Singapore is expected to adopt IFRS 18 into SFRS(I), with an effective date for annual periods beginning on or after 1 January 2027.

Given the extent of the changes—and the requirement to restate comparative information—entities should begin preparing well ahead of the effective date.

Summary of Key Changes Under IFRS 18

Mandatory New Profit or Loss Categories

IFRS 18 replaces the traditional P&L format with three standardised, prescriptive categories:

  • Operating

  • Investing

  • Financing

All income and expenses must be reclassified into these categories based on detailed application guidance. This creates greater consistency across entities and industries, but requires extensive remapping of existing accounts.

Introduction of Management-Defined Performance Measures (MPMs)

IFRS 18 formally defines and regulates Management-Defined Performance Measures, which are subtotals of income and expenses that:

  • Are used in public communications outside the financial statements; and

  • Reflect management’s view of an aspect of financial performance of the entity as a whole.

Examples include Adjusted EBITDA, underlying profit, or other non-GAAP measures.

Entities must now:

  • Clearly define each MPM

  • Reconcile each MPM to the nearest IFRS-defined subtotal

  • Disclose explanations, rationale and consistency of application

This framework aims to enhance transparency around customised performance metrics.

Enhanced Disaggregation Requirements

IFRS 18 significantly raises the threshold for disaggregation. Entities must:

  • Break down material income and expense items into more granular components

  • Avoid overly broad or “catch-all” line items

  • Provide entity-specific breakdowns, not boilerplate disclosures

This will require detailed mapping and improved data capture within accounting systems.

Disclosure of “Unusual” Income and Expenses

Entities must separately disclose items that:

  • Are not expected to recur in the near term, and

  • Significantly affect the understanding of financial performance.

The standard prescribes how these items must be described and reconciled, improving comparability across entities.

Key Implications for Singapore Companies

1. Mandatory Restatement of Comparatives

For 2027 reporting, entities must restate all comparative periods using the new IFRS 18 structure. This includes:

  • Reclassifying prior-year income and expenses

  • Reconstructing MPMs for earlier periods

  • Providing comparative disclosures for “unusual” items

Practically, companies must be IFRS 18-ready for 2026 financials.

2. Revisions to the Chart of Accounts and Accounting Policies

To align with the new categories, entities will need to:

  • Re-map GL accounts to operating, investing, and financing classifications

  • Update internal accounting policies

  • Establish rules for consistent classification across reporting periods

3. ERP, System and Reporting Impacts

IFRS 18 will require:

  • More granular data collection

  • New P&L mapping structures

  • Additional reporting templates and automated reconciliations

Early system assessment is critical to avoid bottlenecks close to adoption.

4. Potential Impact on KPIs, Covenants and Investor Communication

New required subtotals and category definitions may affect:

  • KPI calculations (e.g., operating profit, EBITDA variants)

  • Bank covenants tied to performance metrics

  • Investor presentations and management commentary

Entities should evaluate these impacts proactively.

5. Expanded Narrative and Note Disclosures

IFRS 18 introduces new disclosure obligations relating to:

  • MPM definitions and reconciliations

  • Category-specific accounting policies

  • Disaggregation analyses

  • Unusual income and expense items

Disclosure preparation will require coordination across finance, operations, and management.

Preparing for 1 January 2027: Actions to Take Now

1. Conduct an IFRS 18 Gap Assessment

Evaluate:

  • Required P&L restructures

  • Classification impacts

  • Disaggregation and data gaps

  • Effects on KPIs, covenants, and management reporting

2. Begin Comparative Restatement Planning

Start re-mapping trial balances for 2024–2026 to ensure:

  • Sufficient granularity for retrospective presentation

  • Availability of historical data for MPM reconciliations

3. Redesign Chart of Accounts and Update Policies

Define the entity’s approach to:

  • Category classification

  • Identification of unusual items

  • MPM definitions, governance and reconciliation processes

4. Upgrade ERP and Reporting Tools

Ensure systems can:

  • Capture the granularity required

  • Track category-level information

  • Produce IFRS 18-compliant statements and disclosures

5. Train Finance Teams and Engage Stakeholders

Training should focus on:

  • New P&L structure

  • Disaggregation requirements

  • MPM rules and disclosure obligations

Stakeholders such as audit committees, banks, and investors should be briefed early.

6. Perform Dry Runs Before 2026

Trial restatements help identify:

  • Classification inconsistencies
  • Missing data

  • System limitations

  • Impacts on covenants and KPIs

Conclusion — Early Preparation Is Critical

Although IFRS 18 applies from 1 January 2027, the need to restate comparative periods means companies must begin preparing well in advance. Early assessment, system readiness, and robust policy development are essential to ensure a smooth transition.

If you require assistance with IFRS 18 impact assessments, comparative restatement planning, policy updates, or full implementation support, our team is ready to help.

ACRA Compliance Mandates for RORC, ROND and RONS

Under the Companies and Limited Liability Partnerships (Miscellaneous Amendments) Act 2024 (CLLPMA), the Accounting and Corporate Regulatory Authority (ACRA) introduced statutory disclosure requirements designed to enhance corporate transparency:

  • Effective: 16 June 2025

This regulatory framework tightens statutory reporting obligations for the Register of Registrable Controllers (RORC), Register of Nominee Directors (ROND), and Register of Nominee Shareholders (RONS). It eliminates historical setup grace periods, mandates central ACRA lodgments, and significantly increases non-compliance penalties.

Understanding these requirements is essential for company officers, business owners, and corporate groups to ensure ongoing statutory compliance and audit readiness.

1. Key Statutory Requirements

To align Singapore with international Financial Action Task Force (FATF) Anti-Money Laundering (AML) standards, ACRA enforces the following statutory mandates:

  • Day-1 RORC Maintenance: Entities incorporated on or after 16 June 2025 must establish, maintain, and lodge their Register of Registrable Controllers (RORC) on the date of incorporation via BizFile+.
  • Central Register Lodgment (ROND & RONS): Companies must lodge nominee director and nominee shareholder particulars—including the identities of underlying nominators—directly into ACRA’s Central Registers.
  • Transition for Existing Companies: Companies incorporated before 16 June 2025 have until 31 December 2025 to lodge their nominee director and nominee shareholder information with ACRA.
  • Annual Verification of Controllers: Each year, companies must send every registrable controller a notice, using ACRA’s prescribed template, asking whether their particulars have changed or are still correct. Controllers must return a signed and dated confirmation.
  • Faster Updates: Changes to a controller’s particulars must be recorded within 7 calendar days of the controller’s confirmation, replacing the previous 2-business-day rule. If a controller does not reply within 30 days of the notice, the 7 days start after that 30-day period ends.

2. Public Transparency vs. Data Privacy

ACRA balances regulatory transparency with commercial data protection:

  • Public Business Profile: A director’s or shareholder’s nominee status is publicly disclosed on the company’s BizFile+ Business Profile.
  • Confidential Central Registers: The specific identities of underlying Nominators or Ultimate Beneficial Owners (Controllers) submitted to ACRA remain strictly non-public. This data is accessible only to public agencies and law enforcement authorities for regulatory oversight.

3. Statutory Penalties for Non-Compliance

ACRA has significantly increased fine structures for default:

  • Fines Up to S$25,000 Per Offence: Failure to set up, maintain, update, or lodge accurate RORC, ROND, or RONS details carries statutory fines of up to S$25,000 per offence.
  • False or Misleading Information: A new offence applies to giving false or misleading information to ACRA without due diligence, with fines of up to S$25,000.
  • Officer Liability: Both the company and its officers, including directors and company secretaries, may be liable for these offences.

Information in this article is correct as at June 2025.

Accounting for Cryptoassets

Companies Are Increasingly Investing in Cryptoassets – What Does This Mean for Accounting?

In recent years, the investment landscape has evolved rapidly, with businesses showing growing interest in cryptoassets. Once considered niche, cryptoassets like Bitcoin and Ethereum have become part of mainstream finance. Major companies are making headlines for allocating a portion of their treasury to digital assets, signaling a shift in how corporate funds are being diversified.

Notable Companies Investing in Cryptoassets

Some prominent examples of companies that have invested in cryptoassets include:

  • Tesla Inc. – Made headlines in 2021 with its US$1.5 billion investment in Bitcoin.
  • MicroStrategy – A pioneer in corporate crypto investment, with billions of dollars held in Bitcoin.
  • Block Inc. (formerly Square Inc.) – Has invested significantly in Bitcoin as part of its belief in the asset’s potential.
  • Coinbase – While a cryptocurrency exchange, it also holds substantial cryptoassets on its balance sheet. 
  • Singapore-based DBS Bank – Launched a digital exchange and has exposure to tokenised assets, reflecting local market interest.

These moves signal increased corporate confidence in cryptoassets, but they also bring new challenges—especially in financial reporting.

Accounting for Cryptoassets: Summary of ISCA Guidance

The Institute of Singapore Chartered Accountants (ISCA) has issued FRG 2 – Accounting for Cryptoassets from a Holder’s Perspective, which provides useful guidance for entities on how to account for such holdings.

Although cryptocurrencies are often referred to as “digital currencies,” they typically do not meet the definition of cash or cash equivalents under SFRS(I) 1-7, because they are not legal tender and are not widely accepted as a medium of exchange. In addition, they do not qualify as financial assets under SFRS(I) 9, as they do not give rise to a contractual right to receive cash or another financial asset.

Possible Accounting Treatments for Cryptoassets

CryptocurrencyUtility Token Asset Token Security Token
Nature“A digital or virtual currency that uses cryptography for security.

Cryptocurrencies are used as payment for acquiring goods or services or transfer of funds.
Utility tokens provide the holder with rights to access a product or
service.
Asset tokens provide the holder with rights to an asset.

Rights to assets may be split among many holders by “tokenising” them. In this way, the issued tokens, called asset tokens, indicate rights over a stake in these underlying assets.
Security tokens provide the holder with rights to a security.

Security tokens are similar in nature to an interest in the debt or equity of the issuer by, for instance, giving the holder the right to a share of future profits or cash flows.
GuideThe holding of a cryptocurrency is accounted for as inventory under FRS 2 Inventories if an entity holds it for sale in the ordinary course of business or if the entity is a broker-trader of cryptocurrencies. If FRS 2 is not applicable, the holding is accounted for as an intangible asset under FRS 38 Intangible Assets.If FRS 2, FRS 38 or FRS 109 do not apply, an entity considers recognising the utility token as a prepayment if it represents payment that has been made before receiving the product or service.An entity applies the FRS relevant to the underlying asset if the asset token represents control over the underlying asset.An entity applies FRS 32 to consider whether a security token is a financial asset and if yes, applies FRS 109 to recognise and measure it in the financial statements.
FRS 2 Inventories
SFRS(I) 2 Inventories
If the entity holds it for sale in the ordinary course of
business or if the entity is a
broker-trader of
cryptocurrencies
If the entity holds it for sale in the ordinary course of business or if the entity is a broker-trader of cryptocurrenciesThe relevant FRS depends on the underlying asset, and not the asset tokenIf it meets the definition of a
financial asset in FRS 32
FRS 38 Intangible Assets
SFRS(I) 1-38 Intangible Assets
If it meets the definition and
recognition criteria of an intangible asset and FRS 2 is not applicable
If it meets the definition and recognition criteria of an intangible asset and FRS 2 and FRS 109 are not applicableThe relevant FRS depends on the underlying asset, and not the asset tokenNot applicable
FRS 116 Leases
SFRS(I) 16 Leases
Not applicableIf it represents a right to use
an underlying asset for the
lease term
The relevant FRS depends on the underlying asset, and not the asset tokenNot applicable
PrepaymentNot applicableIf it represents payment
made in advance of the entity
obtaining a right to access
goods or receiving services
The relevant FRS depends on the underlying asset, and not the asset tokenNot applicable

Conclusion

Cryptoassets are gaining traction in corporate finance, but they challenge traditional accounting approaches. ISCA’s FRG 2 helps ensure consistent, transparent classification and reporting. Each case requires judgment based on substance over form.

If your company holds or plans to hold cryptoassets, we’re here to guide you through proper classification and disclosure.

FORTITUDE BUDGET 2020

Job Support Scheme ("JSS")​

Current Treatment​

New Treatment​

The temporary enhancement to  the JSS for the month of April 2020 will raise the wage support to 75% in that month. This will apply to the first S$4,600 of gross monthly wages paid to local workers (Singapore Citizens and Permanent Residents) in all sectors.

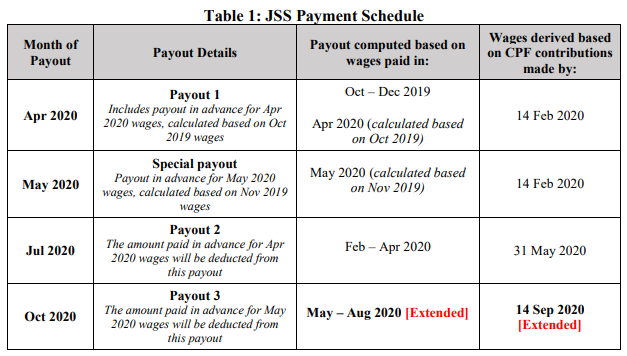
The first JSS payout (“Payout 1”) has been brought forward to  April 2020.

For April 2020 payment, the government will give an Cash Grant of up to 75% of Oct 2019 wages. Subsequently, the Cash Grant in July 2020 will be adjusted downwards by 50% of Oct 2019 wages.

Extended for 1 more month to cover wages paid in August 2020, bringing a total coverage to 10 months of wages. The support for August 2020 wages will be paid
out in October 2020 (see Table 1 for an overview of the JSS payment schedule).

  • 25% to 75% of the first $4,600 of wages for each local employee

Only employers who are not  allowed to resume operations will continue to receive 75% support for wages paid to local employees, during the period for which they are not allowed to resume operations, or until August 2020, whichever is earlier. Pro-ration will be applied if operations
resume in the middle of the month.

Increased support for some affected sectors (e.g. aerospace, retail, marine and offshore) from 25% to 50% or 75%

SGUnited Jobs

Current Treatment

New Treatment

10,000 jobs will start with the public sector recruiting for long-term roles in essential services such as social services, early childhood education and infocomm technology.

Temporary jobs to handle the increase in Covid-19-related operations will also be available in roles such as health declaration assistants and temporary management support officers.

Private sector job opportunities will also be identified together with the Singapore Business Federation and other trade associations and chambers. 

There will be a series of SGUnited Jobs Virtual Career Fair (VCFs) upcoming up.Details of the VCF is available here: mycareersfuture.sg

40,000 jobs aimed to be created in 2020 of which about 15,000 openings will be in the public sector. These consist of a variety of long-term and short-term roles, to meet future and immediate needs. 

The public sector is bringing forward agencies’ hiring plans, creating jobs in new capabilities and functions, and creating short-term jobs arising from COVID-19 operations. The public sector will also provide two-year positions to local jobseekers and train them in key capability areas, to eventually place them in relevant private sector jobs.

The relevant Government agencies will work with businesses to create about 25,000 jobs. To help jobseekers
continue to access good longer-term job opportunities, agencies will also work with programme partners to scale up the capacity of career conversion programmes, including the Adapt and
Grow programmes, to more than 14,000 places this year, especially in growth sectors such as Infocomm & Technology and Financial Services.

SGUnited Traineeships and Mid-Career Traineeships

Current Treatment

New Treatment

Workforce Singapore (WSG) will co-share manpower costs with enterprises that offer up to 8,000 traineeships targeted at local first-time jobseekers this year.

Firms that offer traineeships targeted at local first-time job seekers this year can receive funding from government agency Workforce Singapore (WSG) under this SGUnited Traineeships programme.

These will include science and technology stints in research and development labs, deep-tech start-ups, accelerators and incubators, said DPM Heng.

Participants will receive an allowance co-funded by the Government and firm they are attached to.

Given the strong interest from businesses and public agencies, the Government aims to more
than double the number of traineeships available for our young locals this year, from 8,000 to 21,000. Of these, there will be new traineeship positions in our R&D sector, including our universities, A*STAR research institutes, AI Singapore, and local deep-tech startups through SG Innovate. Recent and new graduates can apply for these opportunities on MyCareersFuture.sg from 1 June 2020 onwards.
To cater to the needs of mid-career individuals, we will create a new SGUnited Mid-Career Traineeships programme, to facilitate about 4,000 more traineeships for unemployed midcareer jobseekers looking to gain meaningful industry-relevant work experience and boost employability for future job opportunities. This will be on top of the 21,000 opportunities under
the SGUnited Traineeships. More details will be provided in due course.

Overall, both programmes aim to facilitate about 25,000 traineeship opportunities for our young locals and experienced professionals.

SGUnited Skills

Current Treatment

New Treatment

Not applicable.

The SGUnited Skills (SGUS) programme is a full-time training programme ranging from 6 to 12 months. The programme will comprise certifiable courses delivered by companies and the Continuing Education Training (CET) Centres, including Institutes of Higher Learning. The training courses are designed in partnership with the industry, and can include companies
co-delivering and co-designing the programme with training providers. Trainees will also have the chance to apply the skills learnt during the programme, through opportunities like
workplace immersions and industry projects.

Trainees will also benefit from employment facilitation efforts offered by training providers. To facilitate transition to employment as and when job opportunities are present, the SGUS
programme will be conducted in a modular format.


Trainees will also receive a training allowance of $1,200 per month for the duration of the programme, to cover basic subsistence expenses. Course fees will be highly subsidised, to
keep SGUS affordable. Individuals can use their SkillsFuture Credit to offset the course fees.


More details on the SGUS programme will be provided by the Ministry of Education. 

Hiring Incentive

Current Treatment

New Treatment

Employers who hire local workers aged 40 and above through eligible reskilling programmes. For each eligible worker hired, the employer would receive 20% salary support for six months, capped at $6,000 in total. Eligible reskilling programmes were the Professional Conversion Programmes (PCPs), Place-and-Train (PnT) programmes for rank-and-file workers, and career transition programmes by Continuing Education and Training (CET) centres.

The Hiring Incentive will be enhanced to cover local workers of all ages, with increased support for those aged 40 and above. We will also expand the list of eligible reskilling and training programmes. The enhanced Hiring Incentive will be applicable to any hire from eligible reskilling programmes from 27 May onwards. A summary of the enhancements to the Hiring Incentive is in Table 2. 

Foreign Worker Levy Waiver & Rebate

Current Treatment

New Treatment

  • Waiver of monthly Foreign Worker Levy (FWL) due in April 2020 to help firms with cash flow
  • FWL rebate of $750 in April 2020 from levies paid this year, for each Work Permit or S Pass holder

Extended by up to 2 months for businesses that are not allowed to resume operations after the circuit breaker.

  • 100% waiver and $750 rebate in June 2020
  • 50% waiver and $375 rebate in July 2020

Deferment of Higher CPF Contribution Rates

Current Treatment

New Treatment

Not applicable.

To help businesses manage costs in these challenging times, the Government will defer the planned increase in CPF contribution rates for senior workers by one year, from 1 January 2021 to 1 January 2022. The CPF Transition Offset scheme will similarly be deferred until after the higher contribution rates take effect.

Expanding Rental Relief for SMEs

Current Treatment

New Treatment

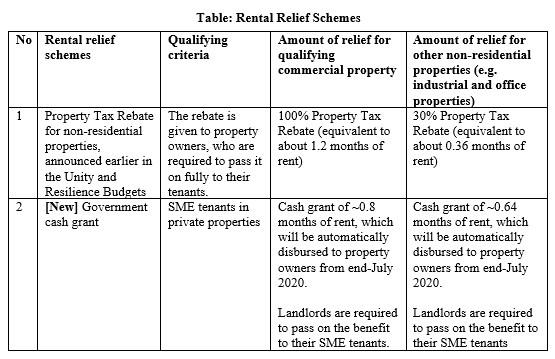
  • 1-month rental waiver for office, industrial, and agriculture tenants of Government agencies.
  • Laws to ensure property owners pass on Property Tax rebate to tenants.

$2 billion in cash grants to help SME tenants with rental costs

Including the Property Tax Rebate for 2020, Government will:

  • Offset 2 months’ rental for qualifying SME tenants of commercial properties
  • Offset 1 month’s rental for qualifying SME tenants of industrial and office properties

Rental Relief for Government Tenants

Current Treatment

New Treatment

Stallholders at hawker centres and markets managed by the National Environment Agency (NEA) will be given three months’ worth of rental waiver, with a minimum waiver of $200.

Commercial tenants in other government-owned or managed facilities will be provided with two months’ worth of rental waivers. 

Other Non-Residential Tenants. Government agencies such as JTC, SLA, HDB, URA, BCA, NParks, and PA will provide half a month’s worth of rental waiver to eligible tenants of other non-residential premises who do not pay Property Tax. Eligible tenants/lessees may include those in premises used for
industrial or agricultural purpose, or as an office, a business or science park, or a petrol station.

Additional 2 months of rental waivers for commercial tenants and hawkers. The total rental waiver will now be four months for commercial tenants. Stallholders in hawker centres and markets managed by Government
agencies will get a total of five months of rental waivers. 

For industrial, office, and agricultural tenants of Government agencies, one more month of rental waiver will be provided. A total of two months of rental waiver will be received.

Financing Support for Promising Startuprs

Current Treatment

New Treatment

  • Enterprise Financing Scheme – SME Working Capital Loan
  • Enterprise Financing Scheme – Trade Loan
  • Loan Insurance Scheme
  • Temporary Bridging Loan Programme (TBLP)

$285 million of additional financing support for promising startups by co-investing with the private sector

  • On top of $300 million set aside under the Unity Budget for deep-tech startups

Adopting e-Payments

Current Treatment

New Treatment

Not applicable.

Bonus of $300 per month over 5 months to encourage adoption of e-payments by stallholders in 

  • Hawker centres
  • Wet markets
  • Coffee shops
  • Industrial canteens

Digital Resilience Bonus

Current Treatment

New Treatment

  • E-invoicing Registration Grant
  • Advanced Digital Solutions
  • SMEs Go Digital

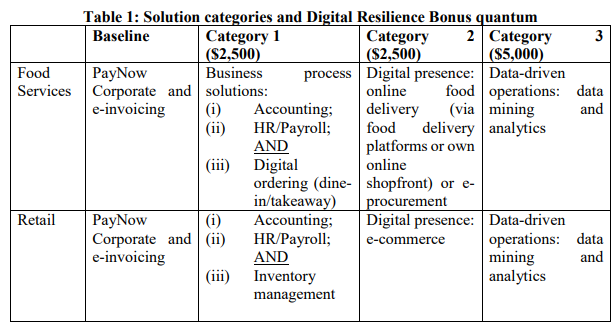
Eligible businesses can receive a payout of up to $5,000 if they adopt PayNow
Corporate and e-invoicing, as well as business process or e-commerce solutions.

Businesses which already have basic digital capabilities, should deepen their digital transformation. We will help them make use of advanced digital tools in an
integrated way. 

  • The Digital Resilience Bonus will have an additional tier of $5,000 for F&B and retail businesses which also incorporate advanced solutions.

National Innovation Challenges

Current Treatment

New Treatment

Not applicable.

Encourage partnership with the private sector for industry-led solutions to reopen Singapore safely

Covid-19 Support Grant (CSG)

Current Treatment

New Treatment

The scheme eligibility criteria are as follows:

  • Singapore Citizens or Permanent Residents, aged 16 years and above,
  • who are presently unemployed due to retrenchment or contract termination as a result of the economic impact of the COVID-19 situation, and meet all of the following:
  • Had a monthly household income of not more than $10,000, or per capita household income not more than $3,100 per month prior to unemployment;
  • Lives in a property with an annual value of not more than $21,000; and
  • Not currently receiving ComCare Short-to-Medium Term Assistance(SMTA) or ComCare Interim Assistance.
  • The applicant must have been employed as a full-time, or part-time permanent, or contract staff prior to unemployment.

Successful applicants will receive a monthly cash grant of S$800, for three months.

The scheme will be open for application from May 2020 to September 2020.

Individuals who are eligible may submit their application at their nearest Social Service Office.

Support for Singaporeans and PRs who 

  • Have lost their jobs;
  • Are placed on no-pay leave; or,
  • Face significantly reduced salaries

Up to $800 per month for 3 months for eligible recipients

Solidarity Utilities Credit

Current Treatment

New Treatment

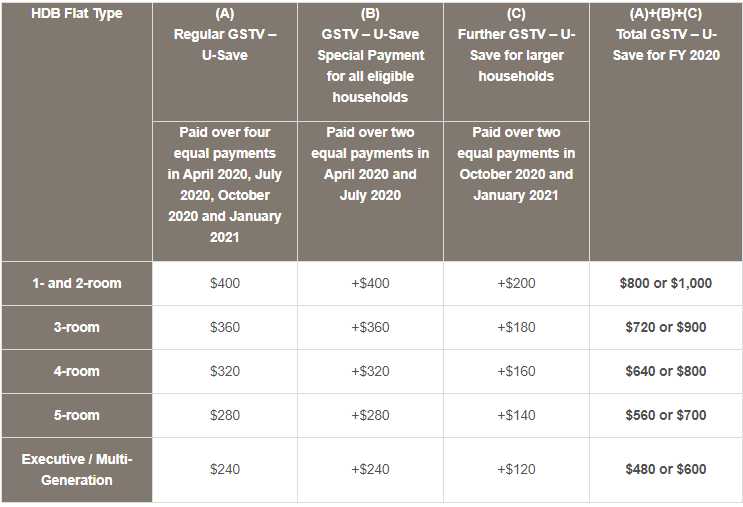
  • One-off $100 Solidarity Utilities Credit for each household with at least one Singapore Citizen
  • Covers all property types
  • Will be credited in households’ July or August 2020 utilities bills with SP Group
  • Larger households with five or more members get more, and can receive up to $1,000 in U-Save rebates this year

For Students and Seniors - Fostering Digital Inclusion

Current Treatment

New Treatment

Not applicable.

For Students

  • Accelerated timeline for all secondary school students to own a digital leaning device

For Seniors

  • Seniors Go Digital movement to build digital literacy through one-to-one coaching and small-group learning
  • Financial support for lower-income seniors to own digital devices

Enhanced Fund-Raising (EFR) Programme

Current Treatment

New Treatment

Totalisator Board (TB) provides 40% matching on donations raised by charities, capped at $100,000 per fund-raising project. For example, an eligible charity project which raises $10,000 will receive $4,000 in matching grants from TB. This applies to all modes of donations, including those through approved digital platforms such as Giving.sg or the websites of the individual charities.

  • Dollar-for-dollar matching on eligible donations raised between 1 April 2020 to 31 March 2021, capped at $250,000 matching per charity
  • Additional $100 million top-up to strengthen support for charities
To be eligible, the charity must be registered with the Commissioner of Charities. Qualifying donations are those raised through approved fund-raising projects commencing from 1 April 2020 to 31 March 2021 (both dates inclusive). In addition, the fund-raising project should not have benefited from other Government matching funds, such as the Cultural Matching Fund or the Bicentennial Community Fund.

Invictus Fund

Current Treatment

New Treatment

Not applicable.

The Invictus Fund was set up by the National Council of Social Service (NCSS) to channel donations to SSAs which deliver critical social services to vulnerable groups during COVID19. The Invictus Fund is supported by donations raised through Community Chest, which
receives 20% matching from the Bicentennial Community Fund.

As at 22 May 2020, $6.2 million has been raised for the Invictus Fund. 171 SSAs applied for the Invictus Fund in the first round of applications.


The Government will provide a top-up of $18 million to the Invictus Fund to enhance support for SSAs which continue serving their beneficiaries during this period. 

How to pass property tax rebate from property owner to tenant

Resilience Budget on property tax​

As part of the Resilience Budget announced on 26 Mar 2020, qualifying nonresidential properties (“qualifying properties”) will be granted up to 100% of property tax rebate for the period of 1 Jan 2020 to 31 Dec 2020.

For most properties that are eligible for 100% property tax rebate, this is equivalent to slightly more than one month’s rental.

Owners of qualifying properties are required to unconditionally and fully pass on to their tenant(s) the rebate for the property tax account that is attributable to the rented property, by either reducing or offsetting current or future rentals or through a payment to their tenant(s), within the prescribed time frame.

Prescribed Amount of Rebate for Passing on – Where the Whole Property is Leased or Licensed to Single Tenant​

There are two options for the property owner to fulfil his obligation in passing on the prescribed amount of rebate to his tenant(s), Option 1A and Option 2A.

Option 1A​

The owner must pass on to a tenant the total of the sums calculated for each month of the year 2020 in which the tenant rents the property.

PTR / 12 X D/D(Month)

“PTR” is:
(a) the rebate amount for the property before any change in circumstances occurs;
(b) Zero, if there is no rebate amount mentioned in (a); 

“D” is the number of days in the month for which the tenant is a prescribed lessee or prescribed licensee of the property;

“D(Month)” is the number of days in the month

Option 2A​

The property owner may choose to pass on the whole of the rebate amount of the property to:
(a) The tenant of the property on 3 April 2020;
(b) If there is no tenant as mentioned in (a) for the property, the first tenant of the property in the period between 4 April 2020 and 31 July 2020 (both dates inclusive); or
(c) If there is no tenant of the property, in paragraphs (a) or (b), then only Option 1A applies.

Prescribed Amount of Rebate for Passing on – Where Part of Property is Leased or Licensed to Tenant or Different Parts of the Property are Leased or Licensed to Different Tenants ​

There are two options for the property owner to fulfil his obligation in passing on the prescribed amount of rebate to his tenant(s), Option 1B and Option2B.

The property owner has to adopt the same option, either Option 1B or Option 2B, in respect of the different parts of the property.

Option 1B​

The owner must pass on to a tenant the total of the sums calculated for each month of the year 2020 in which the tenant is such a lessee or licensee.

𝑁𝑅 × 10% × 𝑃𝑇𝑅(%) × 𝐷/𝐷(𝑀𝑜𝑛𝑡ℎ)

“D” is the number of days in the month for which the tenant is a prescribed lessee or prescribed licensee of the part of the property;
“D(Month)” is the number of days in the month;
“NR” is the net rent* payable by the tenant for the part of the property for the month;
“PTR(%)” is the rate of the property tax rebate granted for the part of the property

*This net rent is the rent, licence fee or similar payment payable by the prescribed lessee or prescribed licensee of the property or part of the property to the owner of the property under the lease or licence agreement between the prescribed lessee or prescribed licensee and the owner which (a) Includes the following amounts payable under the agreement:
(i) any amount determined by the gross turnover (GTO)** of any business carried on by the lessee or licensee at the property or part of the property;
(ii) fees for repair, insurance, maintenance and upkeep of the property or part of the property, and property tax payable by the owner; but
(b) Excludes the following amounts payable under the agreement:
(i) any amount in respect of the provision of services (e.g. cleaning,
refuse disposal and advertising and promotion) by the owner to the lessee or licensee; and (ii)any goods and services tax.

Where for any month, the month amount plus previous months cumulative amount determined using Option 1B for every tenant  would together exceed the rebate amount for the property, the amount of that rebate amount less the previous months cumulative amount is to be passed on to each tenant on a proportionate basis if there is more than one subject tenant; or the tenant in whole, if there is only one tenant

Option 2B​

The property owner may choose to pass on the rebate for each part of the property as follows:
(a) Where the part of the property is granted a property tax rebate of 100% or 60%, an amount of at least 
1.2 x AR
(b) Where the part of the property is granted a property tax rebate of 30%, an amount of at least 
0.36 x AR
to the tenant as follows:

(i) The tenant of the part of the property on 3 Apr 2020;
(ii) If there is no tenant as mentioned in paragraph 9.17(i) for the part of the property, the
first tenant of that part in the period between 4 Apr 2020 and 31 Jul 2020 (both dates inclusive); or
(iii) If there is no tenant of the property, in paragraphs 9.17(i) or (ii), then only Option 1B applies. 

“AR”’ is the average net rent* per month payable by the tenant for the part of the tenant’s lease or licence that falls in the period starting on 1 Jan 2020 and the last day of the month immediately before the month in which the owner passes on or begins to pass on the benefit (both days inclusive). If the duration of the lease or licence in the period 1 Jan 2020 and the last day of the month in which the owner passes on or begins to pass on the rebate (both days inclusive) is less than one month, the net rent payable for that part of the month must be used to determine a proportionate amount for the whole month, which is then to be treated as the average net rent per month for the period.

Where the sum total of the amounts determined for all such tenants of the property would exceed the rebate amount for the property, then the amount of rebate must be passed to those tenants on a proportionate basis.


IRAS – Extended Filing Deadline [Updated]

Due to the extended Circuit Breaker to 1 June 2020, IRAS is providing an automatic extension of deadlines for tax filing for individuals and businesses.

Tax TypeOriginal Filing DeadlineExtended Filing Deadline New
Income Tax for Individuals (including sole proprietors and partnerships)18 Apr 202031 May 2020
Income Tax for Trusts, Clubs and Associations15 Apr 202030 Jun 2020 Updated
Estimated Chargeable Income (ECI) for companies with Financial Year ending Jan 202030 Apr 202030 Jun 2020 Updated
Estimated Chargeable Income (ECI) for companies with Financial Year ending Feb 202031 May 202030 Jun 2020 Updated
GST Returns for accounting period ending Mar 202030 Apr 202011 May 2020
S45 Withholding Tax Forms due in Apr 202015 Apr 202015 May 2020
Tax Clearances for foreign employee in Apr 2020– 30 Jun 2020 Updated
Tax Clearance for foreign employees due in May 2020– 30 Jun 2020 Updated

SUPPORT MEASURES DURING EXTENDED CIRCUIT BREAKER PERIOD UNTIL 1 JUNE 2020

On 21 April 2020, the Multi-Ministry Taskforce announced that it would extend the circuit breaker period until 1 Jun 2020 (inclusive).

Supporting Workers and Businesses

The Government will extend the 75% JSS on the first $4600 of gross monthly wages for local employees across all sectors for another month, i.e. in the month of May 2020. This enhanced payout for May 2020 will be disbursed by end-May 2020 via PayNow or having existing GIRO arrangements with IRAS. Other employers will start receiving their cheques in early-June. The Government encourage all employers to sign up for PayNow to receive payouts faster.

Similar to the arrangement for April, the 75% subsidy for May 2020 will first be computed and disbursed based on November 2019 wages, thereby ensuring speedy disbursement. Subsequently, we will adjust future JSS payouts to account for actual wages paid in May 2020, relative to November 2019. 

Employers who put local employees on mandatory no-pay-leave or retrench them will not be entitled to the enhanced JSS payout for those employees.

Jobs Support Scheme (“JSS”) to cover Shareholder-Directors

The Government has extended the Jobs Support Scheme, to cover wagers of employees of a company who are also shareholders and directors of the company. 

This support is only applied to companies that were registered on or before 20 April 2020, and for the wages of shareholder-directors with Assessable Income of $100,000 or less for Year of Assessment 2019. The May 2020 and subsequent JSS payouts will include support for qualifying shareholder-directors. The May 2020 payout will also include back-payment for companies with qualifying shareholder-directors whose wages were excluded from the first JSS payout in April 2020.

Foreign Worker Levy Waiver and Rebate extended by 1 month

The Government will extend the Foreign Worker Levy (FWL) waiver and FWL rebate by one month, to ease labour costs of firms that employ foreign workers in this period. 

As with the initial introduction of the waiver and rebate, this assistance will support firms with workers who are unable to work due to the circuit breaker and/or Stay Home Notice (SHN) measures. Firms should use the assistance for their workers’ wages and subsistence needs. MOM will provide further details. 

BUDGET SUMMARY 2020

A summary of Unity, Resilience and Solidarity Budget 2020.

Jobs Support Scheme ("JSS")

The temporary enhancement to  the JSS for the month of April 2020 will raise the wage support to 75% in that month. This will apply to the first S$4,600 of gross monthly wages paid to local workers (Singapore Citizens and Permanent Residents) in all sectors.

The first JSS payout (“Payout 1”) has been brought forward to  April 2020.Employers, who are on PayNow or have a Giro account with IRAS, will receive their payment in mid-April. Other employers will start to receive their cheques
the following week.

Self-Employed Person Income Relief Scheme ("SIRS")

As part of the Solidarity Budget, the Ministry of Manpower (MOM) will enhance the Self-Employed Person (SEP) Income Relief Scheme (SIRS) to  broaden support for SEPs affected by Covid-19 and tide them through this period of economic uncertainty. Eligible SEPs will receive three quarterly cash payouts of $3,000 each in May, July and October. 

1. WIth the two key enhancements, Singaporean SEPs who meet all of the following criteria will be eligible for SIRs:

    • Started work as an SEP on or before 25 March 2020
    • Currently earn a Net Trade Income (NTI) of not more than $100,000.;
    • If SEP also has employment (i.e. dual status worker), the income earned as an employee must be not more than $2,300/month;
    • Live in a property with an AV not more than $21,000; and
    • Do not own two or more properties.

2. For married Singaporean SEPs, the following additional criteria apply::

    • The individual and spouse together do not own two or more properties; and
    • The Assessable Income of his/her spouse does not exceed $70,000.

Care and Support Package

All Singaporeans aged 21 and above this year will receive a one-off Solidarity Payment of S$600 in cash. This will be done by bringing forward S$300 from the earlier announced enhanced Care and Support – Cash, and the Government topping up an additional S$300.

Most eligible citizens will receive their Solidarity Payment by 14 April 2020.

Eligible citizens will be notified of their payment via SMS, from 15 April 2020.

The other cash payouts that were earlier announced in the Resilience Budget under the enhanced Care and Support Package will be paid out in June 2020 (brought forward from August and September 2020).

These include:

  1. Remaining enhanced Care and Support – Cash of S$300 and S$600, for lower- and middle-income adult Singaporeans;
  2. Additional enhanced Care and Support – Cash of $300 for Singaporean parents with at least one Singaporean child aged 20 and below this year; and
  3. PAssion Card Top-up of S$100 for all Singaporeans aged 50 and above this year.
    This will be paid out in cash instead of through physical redemption, in consideration of safe distancing.

Cash Flow & Credit Support for Employers

To support enterprises, the Government will be helping employers with cash flow and credit:

  • Waiver of monthly Foreign Worker Levy (FWL) due in April 2020 to help firms with cash flow
  • FWL rebate of $750 in April 2020 from levies paid this year, for each Work Permit or S Pass holder
  • Laws to ensure property owners pass on Property Tax rebate to tenants.
  • 1-month rental waiver for office, industrial, and agriculture tenants of Government agencies
  • Government’s risk share raised from 80% to 90% for EFS-Trade Loan, EFS-SME Working Capital Loan, and Temporary Bridging Loan Programme (applies to loans initiated from 8 April 2020 till 31 March 2021)

Self-Employed Person Training Support Scheme

The training allowance is increased to S$10.00 an hour with effect from 1 May 2020.

Workfare Income Supplement Scheme ("WIS")

The Workfare Special Payment is increased to S$3,000, which will be paid over two equal payments of S$1,500 each, in July and October 2020.

COVID-19 Support Grant

The scheme eligibility criteria are as follows:

  • Singapore Citizens or Permanent Residents, aged 16 years and above,
  • who are presently unemployed due to retrenchment or contract termination as a result of the economic impact of the COVID-19 situation, and meet all of the following:
  • Had a monthly household income of not more than $10,000, or per capita household income not more than $3,100 per month prior to unemployment;
  • Lives in a property with an annual value of not more than $21,000; and
  • Not currently receiving ComCare Short-to-Medium Term Assistance(SMTA) or ComCare Interim Assistance.
  • The applicant must have been employed as a full-time, or part-time permanent, or contract staff prior to unemployment.

Successful applicants will receive a monthly cash grant of S$800, for three months.

The scheme will be open for application from May 2020 to September 2020.

Individuals who are eligible may submit their application at their nearest Social Service Office,

Deferment of Income Tax Payments for Companies

All companies with Corporate Income Tax (CIT) payments due in the months of April, May and June 2020 will be granted an automatic three-month deferment of these payments. 

The CIT payments deferred from April, May, and June 2020 will instead be collected in July, August, and September 2020 respectively.

No application is required.

Deferment of Personal Income Tax (PIT) Payments for Self-Employed Persons (SEPs)

All SEPs are to file their personal income tax (PIT) returns for YA 2020 by 18 April 2020. SEPs will be granted an automatic three-month deferment of their PIT payments due in the months of May, June and July 2020. The PIT payments deferred from May, June, and July 2020 will instead be collected in August, September, and October 2020 respectively.

Rental Waivers for Tenants in Government-Owned / Managed Non-Residential Facilities

Stallholders at hawker centres and markets managed by the National Environment Agency (NEA) will be given three months’ worth of rental waiver, with a minimum waiver of $200.

Commercial tenants in other government-owned or managed facilities will be provided with two months’ worth of rental waivers. 

Other Non-Residential Tenants. Government agencies such as JTC, SLA, HDB, URA, BCA, NParks, and PA will provide half a month’s worth of rental waiver to eligible tenants of other non-residential premises who do not pay Property Tax. Eligible tenants/lessees may include those in premises used for
industrial or agricultural purpose, or as an office, a business or science park, or a petrol station.

Enhanced Property Tax Rebate for Non-Residential Properties

For the tourism sector:

  • Property Tax Rebate of 100% for the year 2020, for the accommodation and function room components of licensed hotels and serviced apartments, and prescribed Meetings, Incentives, Conventions, and Exhibitions (MICE) venues.
  • International cruise and regional ferry terminals will receive a 100% Property Tax Rebate, and
  • the Integrated Resorts will receive a 60% Property Tax Rebate.

For the aviation sector:

  • 100% Property Tax Rebate for Changi Airport

For other non-residential properties:

  • 30% Property Tax Rebate

Enterprise Development Grant (EDG)

The Enterprise Development Grant (EDG) provides supports projects under 3 categories:

Core Capabilities

Projects under Core Capabilities help businesses prepare for growth and transformation by strengthening their business foundations.

Productivity

Projects under Innovation and Productivity support companies that explore new areas of growth, or look for ways to enhance efficiency.

Market Access

Projects under Market Access support Singapore companies that are willing and ready to venture overseas.

From 1 April 2020 to 31 December 2020, the support level will be raised from up to 70% to up to 80%. For enterprises that are most severely impacted by COVID19, the maximum support level will be further raised to 90% on a case-by-case basis.

Productivity Solutions Grant (PSG)

From 1 April 2020 to 31 December 2020, the maximum support level will be raised from 70% to 80%.

SMEs Go Digital

The SMEs Go Digital programme aims to help SMEs use digital technologies and build stronger digital capabilities to seize growth opportunities in the digital economy. 

From 1 April 2020 to 31 December 2020, the scope of pre-approved digital solutions will be expanded to cover:

  1. Online collaboration tools;
  2. Virtual meeting and telephony tools;
  3. Queue management systems; and
  4. Temperature screening solutions.

The list of digital solutions fro PSG can be found on the Tech Depot

(www.smeportal.sg/content/tech-depot/en/home.html).

SMEs that are looking for visitor registration and contact tracing tools can access free trials provided by the tech industry 

(https://www.imda.gov.sg/bizgodigital).

Stabilisation and Support Package (SSP) - Course fee subsidy

Under the Stabilisation and Support Package (SSP), SSG is providing 90% course fee subsidies and absentee payroll (AP) rates for employers in sectors directly affected by the COVID-19 outbreak (i.e. air transport, tourism, retail, and food services), when they sponsor their workers for eligible courses. 

These enhancements will last for three months.

SG Together Enhancing Enterprise Resilience (STEER)

STEER supports funds set up by the Trade Associations and Chambers (TACs) or industry groupings, with the aim of helping businesses tide over the challenges arising from COVID-19, and to push on with transformation efforts in preparation for economic recovery. 

From 1 April 2020, Enterprise Singapore will match S$1 for every S$2 raised by such industry-led funds, up to S$1 million per fund.

E-invoicing Registration Grant

Businesses registered on the nationwide e-invoicing network on or before 31 December 2020 will receive a one-time grant of S$200. Businesses can register through more than 50 Peppol-ready accounting and ERP solutions. Once registered on the nationwide e-invoicing network, businesses will be able to send and receive e-invoices through the network.

Businesses incorporated on or before 25 March 2020 and registered on the network on or before 31 December 2020 will automatically receive their grant via PayNow Corporate.

There is no need to apply for the grant.

Advanced Digital Solutions

IMDA and Enterprise Singapore will provide up to 80% funding support for enterprises to adopt advanced digital solutions from 1 May 2020 to 31 December 2020.

Examples include:

  1. Advanced security and facilities management systems for buildings – cluster guarding, digital concierges, sensors and analytics for energy management and predictive maintenance, smart toilet systems, and mobile robots for security and/or cleaning. These solutions will help enterprises balance the need to minimise physical contact among staff, with the increased demand for security, cleaning and maintenance. It will also help to integrate security,
    cleaning and maintenance for more seamless facilities management.
  2. Integrated Business-to-Business (B2B) systems to facilitate end-to-end
    transactions between buyers and sellers.
     These would help enterprises transit from  manual/paper transactions to electronic transactions by covering interlinked transactions such as e-procurement, e-invoicing, e-payments, and inventory management.

Enterprise Financing Scheme – SME Working Capital Loan

Maximum loan quantum: S$1,000,000

Maximum repayment
period: 5 years

Government’s risk-share: 80%.

Interest rate: Subject to assessment by Participating Financial Institutions (PFIs)

Principal Payment Deferment: SMEs may request for deferment of principal repayment for 1 year, subject to assessment by PFIs

Enterprise Financing Scheme – Trade Loan

The Enterprise Financing Scheme – Trade Loan supports Singapore-based enterprises’ trade financing needs, which include the financing of short-term import, export, and guarantee needs.

Maximum loan quantum: $10,000,000 per borrower group,

Maximum repayment
period: 1 year

Government’s risk-share: 80%.

Interest rate: Subject to assessment by Participating Financial Institutions (PFIs)

Loan Insurance Scheme (LIS)

The Loan Insurance Scheme helps SMEs secure short-term trade loans by having commercial insurers co-share loan default with Participating Financial Institutions. A portion of the insurance premium paid by SMEs to insurers is supported by the Government.

Maximum loan quantum insured: Subject to assessment by Commercial Insurers and Participating Financial Institutions

Maximum insured period: 1 year

Government’s subsidy on
insurance premium: 80%

Temporary Bridging Loan Programme (TBLP)

The Loan Insurance Scheme helps SMEs secure short-term trade loans by having commercial insurers co-share loan default with Participating Financial Institutions. A portion of the insurance premium paid by SMEs to insurers is supported by the Government.

Sector Coverage: All sectors

Maximum loan quantum: S$5,000,000 per borrower group

Maximum repayment
period: 5 years

Government’s risk-share: 80%

Interest rate: Capped at 5% per annum

Principal Payment Deferment: Enterprises may request for deferment of principal repayment for 1 year, subject to assessment by PFIs

Government fees and charges

All government fees and charges are freeze. i.e. No incremental of fees and charges.

All agencies will continue to collect fees and charges.

Temporary Relief Fund

Some families may require help urgently may apply for Temporary Relief Fund in the month of April, to provide them with immediate financial assistance.

This will be available at Social Service Offices and Community Centres.

SGUnited Traineeships programme

Workforce Singapore (WSG) will co-share manpower costs with enterprises that offer up to 8,000 traineeships targeted at local first-time jobseekers this year.

Firms that offer traineeships targeted at local first-time job seekers this year can receive funding from government agency Workforce Singapore (WSG) under this SGUnited Traineeships programme.

These will include science and technology stints in research and development labs, deep-tech start-ups, accelerators and incubators, said DPM Heng.

Participants will receive an allowance co-funded by the Government and firm they are attached to.

SGUnited Jobs Initiative

10,000 jobs will start with the public sector recruiting for long-term roles in essential services such as social services, early childhood education and infocomm technology.

Temporary jobs to handle the increase in Covid-19-related operations will also be available in roles such as health declaration assistants and temporary management support officers.

Private sector job opportunities will also be identified together with the Singapore Business Federation and other trade associations and chambers. 

There will be a series of SGUnited Jobs Virtual Career Fair (VCFs) upcoming up. More details of subsequent runs of the SGUnited Jobs VCF will be made available at a later date.

https://vcf.mycareersfuture.sg/vcf